Could your business continue if a key person did not return?
Review the people, ownership obligations, and financial commitments your business may need to protect—without pressure or a one-size-fits-all pitch.
- Key-person financial exposure
- Buy-sell funding considerations
- Business continuity and executive benefits
Identify the risks tied to people and ownership
Insurance is only one part of continuity planning. Your attorney and tax professional should review legal and tax matters; we focus on helping you understand appropriate insurance funding options.
Key people
Identify owners or employees whose loss could disrupt revenue, operations, credit, or client relationships.
Ownership transition
Discuss whether an existing buy-sell agreement has a practical and current funding strategy.
Retention priorities
Explore appropriate executive-benefit concepts and the responsibilities they can create.
Clarity in three steps
Describe the business
Share ownership, team size, and your most important continuity concern.
Identify the exposure
Review people, debts, agreements, and financial obligations.
Coordinate the next step
Evaluate suitable insurance options alongside your legal and tax advisers.
A practical conversation with Russell
As a longtime barber and shop owner, Russell understands that continuity planning must work in the real world—not only on paper.
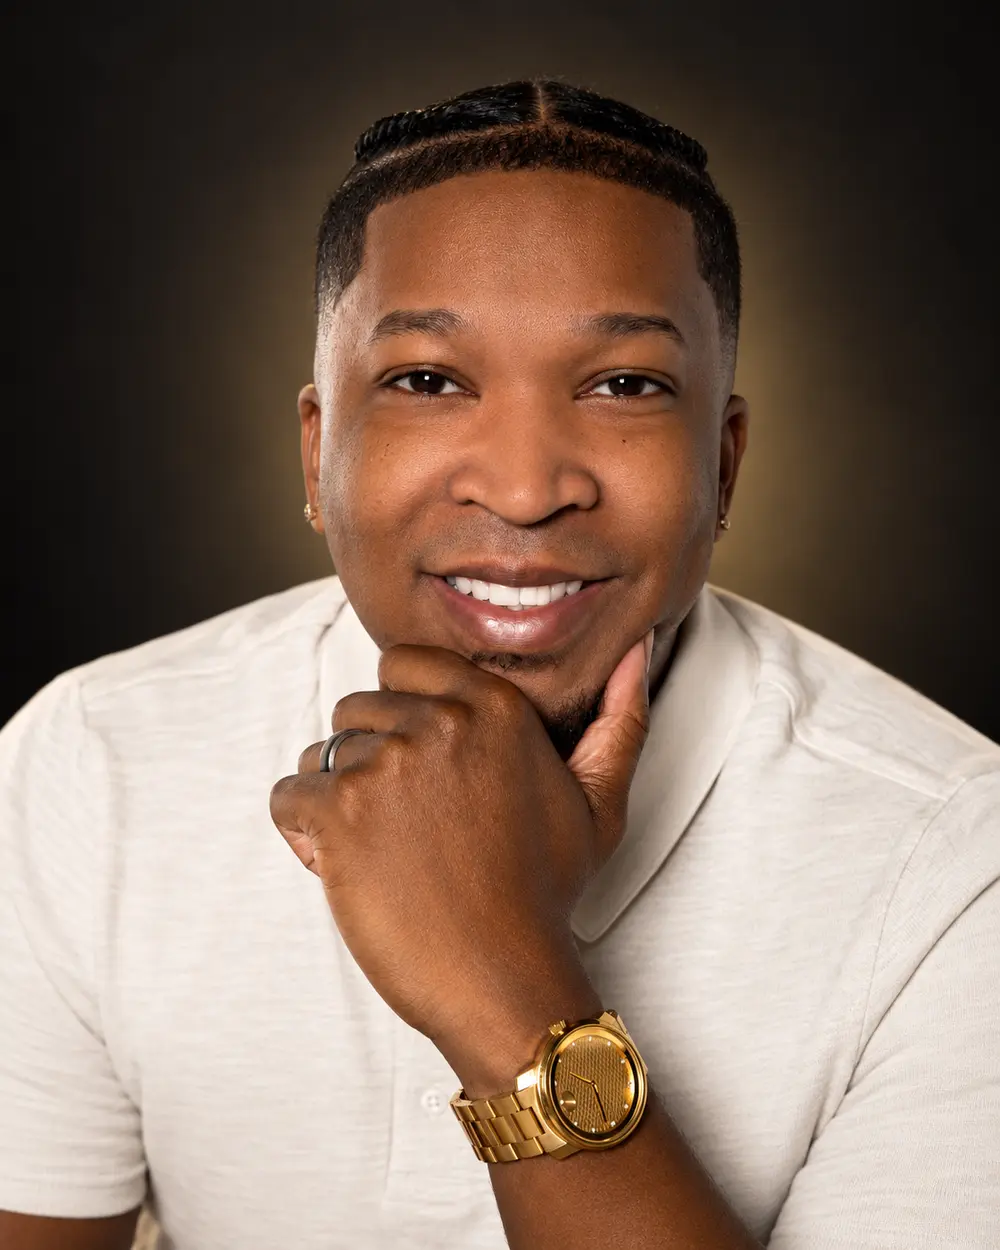
Russell Spry, PresidentLicensed independent insurance professional serving Maryland, Washington, DC, and Virginia.